Green Casa Commercial

Get In Touch

Green Casa Popup Form

Capital Investment

Capital investment assistance services in property management. Get expert guidance here.

Copperfield townhomes for rent in Calgary
Blog, Capital Investment

Copperfield Townhomes vs. Single-Family Rentals: Which Offers Better ROI?

When you are expanding your investment portfolio in southeast Calgary, the decision between buying detached houses and multi-family units is one of the most important ones you will have to make. The choice you make in this regard can either improve or damage your monthly profits. A careful examination of the Copperfield townhomes for rent shows a strong argument in favour of investors who value low costs for exterior maintenance and who want steady, predictable rental yields. Having assisted numerous property owners in considering these very options, I can say that the best choice ultimately depends on your individual investment strategy. Even though single-family homes have higher maximum monthly rents, townhomes do offer a good starting point because they include exterior maintenance. If you want to create a resilient real estate portfolio, it’s essential to examine how tenant demand, maintenance responsibilities, and monthly cash flows compare between these two types of property in this well-established southeast community. Let’s look at the data so that you can invest without any doubts. Comparing Cash Flow and Upfront Capital Requirements The first important factor to look at is the amount of money you have to invest initially compared to the monthly return you can expect. Since single-family detached houses in Copperfield have higher purchase prices, you will need to make a bigger down payment and will end up with higher monthly mortgage payments. Although they rent out at high rates, the greater debt service costs can take a large part of your monthly cash flow in the early years of your mortgage. In contrast, townhouses need a lot less money up front, which makes them suit investors who want to buy a number of units rapidly. Since the prices are lower, the monthly mortgage payments also decrease. Although you have to pay the required monthly condo fees, the steady margin between your debt payments and the rental income generally leads to a higher overall percentage return on the original cash invested. Why Copperfield Townhomes for Rent Attract Low-Turnover Tenants The tenant profiles vary a great deal according to the type of housing. In this area attached housing is particularly popular with young professionals, first-time families and retirees who are downsizing. Members of these groups place a high value on convenience, safety and up-to-date living spaces rather than on large private yards which need mowing on weekends and constant weeding. The fact that the townhomes in Copperfield are designed with low maintenance in mind means that they remain occupied throughout the year and are rented to high-quality tenants. Since the condo corporation looks after exterior landscaping and professional snow removal, renters value this arrangement. By combining a clean and modern interior with an easy-to-manage exterior, the property attracts busy tenants who are much more likely to renew their leases from year to year. Analyzing Detached Copperfield Rental Properties While attached units excel in low-hassle operation, detached homes bring distinct advantages to the table that appeal to long-term wealth builders. Single-family homes attract larger families who are deeply invested in staying within the community for school catchments and sports leagues. These tenants typically sign longer leases and treat the home with a deep sense of pride. Higher Rent Ceilings and Pet Opportunities Detached homes give you the freedom to set higher rental rates, especially if you feature a fully fenced back yard and a double detached garage. In Calgary’s competitive market, allowing pets in a single-family house creates massive leverage. Landlords who welcome dogs can charge premium rent prices and select from a massive pool of qualified applicants who struggle to find pet-friendly housing elsewhere. Capital Appreciation and Land Value From a long-term equity perspective, single-family detached properties generally appreciate faster than attached units. You own the land beneath the structure, giving you superior long-term capital growth. If your primary goal is building substantial equity over a ten-year horizon rather than maximizing immediate monthly cash flow, single-family homes remain a phenomenal choice. Maintenance Responsibilities and Alberta Landlord Rules No matter which asset type you select, maintaining the physical structure is mandatory under Alberta law. According to Alberta’s Residential Tenancies Act, property owners are legally required to keep rental properties in good repair and ensure heating systems function properly to maintain a livable 22°C (72°F) environment. With single-family properties, you are solely responsible for roof repairs, siding, window replacements, and lawn upkeep. With townhomes, the condo corporation manages exterior envelope repairs, roof replacements, and groundskeeping through your condo fees. However, you remain entirely responsible for interior systems, including plumbing, electrical, and appliance upkeep. Marketing Copperfield townhomes for rent with inclusive snow removal and guaranteed maintenance response times is a powerful way to secure top-tier applicants quickly. Essential Maintenance Strategies when Investing in Copperfield Real Estate When investing in Copperfield real estate, proactive maintenance is the single best way to protect your profit margins. Furnace failures during a cold winter freeze lead to emergency service calls, tenant disputes, and costly structural damage from frozen pipes. Establishing a regular HVAC inspection routine protects your cash flow across both single-family homes and townhomes. I always recommend scheduling annual heating checks in late summer or early autumn before the winter rush begins. Replacing furnace filters every two to three months keeps your heating equipment running efficiently, reduces strain on the system, and lowers utility costs. Keeping dated, signed maintenance logs after every check provides proof that you are actively maintaining the property according to provincial standards. Streamlining Operations with Copperfield Calgary Property Management Managing multi-family units or detached homes alongside your daily personal life can quickly turn into a demanding second job. Professional Copperfield Calgary property management bridges the gap between your real estate assets and a truly passive income stream. We handle the complex daily tasks, from enforcing lease agreements to managing condo board communications and tenant requests. Having an expert team on your side ensures your Copperfield rental properties operate at peak efficiency. We know how to price both townhomes and single-family houses accurately against current neighborhood 10

New Brighton Calgary
Blog, Capital Investment

New Brighton Calgary: The Suburban Oasis Offering Smart Investment Potential in 2026

Have you ever driven through a neighbourhood? Felt immediately that you belong there? That feeling is the New Brighton effect. New Brighton Calgary is in the southeast of Calgary. It has become one of the city’s most talked-about communities and that is for good reason. Because New Brighton Calgary was built for families has schools and has a growing rental market investors are drawn to it for both a nice lifestyle and solid returns. No through traffic cuts through New Brighton so the area feels like its small town. In this guide I will walk you through the New Brighton rental market snapshot what makes New Brighton special and why New Brighton deserves a place on your investment radar in 2026. What Makes New Brighton Calgary Special? New Brighton is a family‑oriented community. It has two schools and one junior high plus many playgrounds such as the New Brighton Green Playground and Bumblebee Park. New Brighton also has the New Brighton Athletic Park. That park has four fields for soccer, lacrosse, Frisbee and field hockey a baseball diamond and a skatepark. The center of New Brighton is the New Brighton Clubhouse. It offers programs for all ages, such as chair yoga, tennis, learn‑to‑skate events and teen painting nights. In the heart of New Brighton is New Brighton Central Park. The park centers on a pond. Has a paved walking path around it. The residents’ association in New Brighton is very active. It clears pathways quickly after snowfall. Takes good care of the flower beds and trees. The association offers events, such as an annual Stampede Breakfast. The only shopping centre in New Brighton is the New Brighton Square. The community is a five‑minute drive to Mackenzie Towne Centre. New Brighton is also a 15‑minute drive to Fish Creek Provincial Park. New Brighton Calgary Rental Market Snapshot In April 2026 the median rent for all bedrooms and property types in New Brighton Calgary was $1,924**. That figure is 31% higher than the year. When we look at rent by bedroom size one‑bedroom apartments range from $1,545 to $1,570. Two‑bedroom apartments range from $1,770 to $1,830. Three‑bedroom units average $2,399 and four‑bedroom units average $3,200. Houses for rent in New Brighton cost more with a monthly rent of $2,297. The average price per foot is $1.89. For investors New Brighton shows rental demand in every property type. New Brighton Calgary Real Estate Market The real estate market in New Brighton Calgary is steady. In July 2026 the average house price was $558,092**. The median asking price for homes in New Brighton was $639,900. The median sold price was $625,000. In the past 56 days New Brighton Calgary had 90 new listings. New Brighton has the median sold price among Calgary’s most in‑demand neighbourhoods at $439,000 so it is one of the most accessible entry points for investors. Year over year the average property price in New Brighton Calgary is $615,124, which places it 131st out of 306 Calgary neighbourhoods. In 2026 New Brighton Calgary had 191 transactions. Properties in New Brighton usually sell in 32 days. With a listed price of $553,987 the monthly mortgage payment is about $2,022 – 17% lower than the average list price in Calgary. Schools and Education in New Brighton Calgary Families in New Brighton Calgary have access to schools. New Brighton School (K‑5) offers education and an Early French Immersion option. Dr. Martha Cohen School (Grades 5‑9) serves middle school years for CBE students. The Catholic school in New Brighton is St. Marguerite School (K‑6). Nearby schools are Copperfield School (K‑4) and St. Gianna Catholic School (K‑6). High school students in New Brighton Calgary usually go to schools in communities. Because New Brighton has schools it is especially appealing to families. That appeal leads to stable long‑term demand. New Brighton Calgary Investment Outlook From an investor’s view New Brighton has strong advantages. The median rent of $1,924 in New Brighton  is set to give returns. The good schools and family‑friendly amenities in New Brighton Calgary bring long‑term tenants who care for the property. The athletic park and the clubhouse programs in New Brighton give year‑round activities that keep residents busy. The residents’ association keeps New Brighton community standards high. The drive to downtown Calgary takes 20 minutes but the bus commute is about one hour. For tenants who drive New Brighton gives a mix of suburban life and city access. Conclusion New Brighton is an investment opportunity in Calgary’s southeast. With a rent of $1,924, an average home price near $558,000, good schools, many amenities and strong community engagement New Brighton gives the stability and growth that smart investors want in 2026. The commute to downtown might be a factor. The family‑oriented setup and the active residents’ association, in New Brighton make it a desirable place to live which leads to strong rental demand. Whether you want a home rental or a multi‑family investment New Brighton deserves a closer look. Frequently Asked Questions (FAQs) What is the average rent in New Brighton Calgary in 2026? As of April 2026, the median rent for all bedroom counts and property types in New Brighton Calgary is $1,924. One-bedroom apartments average $1,545-1,570, and two-bedroom apartments average $1,770-1,830. What is the average home price in New Brighton Calgary? As of July 2026, the average house price in New Brighton Calgary is $558,092**, with the median sold price at **$625,000. What schools are in New Brighton Calgary? New Brighton Calgary is served by New Brighton School (K-5 with French Immersion), Dr. Martha Cohen School (Grades 5-9), and St. Marguerite School (K-6 Catholic). What amenities does New Brighton Calgary offer? New Brighton Calgary features New Brighton Athletic Park (sports fields, baseball, skatepark), New Brighton Clubhouse (yoga, tennis, skating), New Brighton Central Park with a pond, and an active residents’ association. Is New Brighton Calgary a good investment? New Brighton Calgary offers strong rental demand, excellent schools, family-friendly amenities, and relatively affordable entry prices compared to other Calgary neighbourhoods, making it an 10

Cash Flow
Blog, Capital Investment

Why Vancouver Investors Are Shifting From Speculation to Cash Flow in 2026

I have bought a rental property and ended up losing money every month. It is not a feeling. For a time investors in Vancouvers hot market could ignore the money they were losing because the value of their properties was going up.. Those days are over. Now making money from rent in Vancouver is the important thing for investors. In 2026 with condo prices 6.8 percent from last year and not many people renting the game has changed. Investors can no longer expect to make money from their properties going up in value. The focus has shifted from buying and selling properties quickly to holding on to them for a time and making money from rent. In this guide I will show you how to make money from properties in Vancouver, where to find properties that make money and how to build a portfolio that generates income from the start. The Old Vancouver Playbook: Why It No Longer Works I am going to be honest with you. The old way of investing in Vancouver does not work anymore. For a time investors bought properties expecting that they would go up in value. You would lose money every month. You would hope that the value of the property would go up. For a long time that worked. The market is different now. The average price of a one-bedroom condo in Vancouver is around $708,200. If you put 20 percent down and get a mortgage with a 4.5 percent interest rate your monthly mortgage payment would be around $3,130. Add the fees for the building, taxes, insurance and maintenance and your total monthly cost would be around $4,007.. The average rent for a one-bedroom condo is only around $2,500 per month. That means you would lose around $1,507 every month. That is $18,084 per year. In a market where condo prices have dropped 6.8 percent relying on the value of the property to go up is a gamble that not many investorsre willing to take. When you are trying to make money from rent in Vancouver this math does not work. What Changed? The Market Has Flipped Several things have happened that have changed the market in Vancouver. First there are a lot of rental units being built. 24,000 Rental units will be available in the next two years. This means that there are options for renters and the prices are going down. Second not as many people are moving to Vancouver as before. The population of British Columbia actually went down by over 41,000 people in 2025. This means that there are not many people looking for rental properties. Third the vacancy rate in Vancouver has gone up to 3.7 percent the highest it has been since 1988. The result is that rents have gone down 9.2 percent from year in Vancouver. Landlords are now offering one to two months of rent to attract tenants. Brand-new rental buildings are struggling to get the rents they expected. As David Venance of Cushman & Wakefield said, “This is a change after a period of high prices it’s not a sign of a weak market. For investors who want to make money from rent in Vancouver it means they need to do things differently. Where to Find Cash Flow in Vancouver in 2026 So where can you actually find properties that make money in Vancouver? It is not easy. It is possible. You can look at buildings with five or more units. The interest rates for these properties are around 3 to 4 percent, which might seem low. The financing available through CMHC’s MLI Select program makes it more attractive. You can also look at places like Surrey and Langley. If you are willing to look outside of Vancouver, these areas offer options for making money from rent. The prices are lower. You can add secondary suites to increase the rent. A legal basement suite in Surrey or Langley can generate $1,800 to $2,400 per month which can cover 40 to 60 percent of your mortgage payment.You can also look at existing apartment buildings with rents. For example The Maples, a 38-unit building in Vancouver has rents that’re 23.51 percent below market. By renovating the units and raising the rents investors can increase the cash flow and value of the property. Laneway houses are another option. A built laneway house in Kitsilano can rent for $3,200 to $4,500 per month. While the upfront cost is high it can pay for itself in 12 to 14 years. Then it is all profit. The MLI Select Game-Changer If you are investing in properties with five or more units CMHCs MLI Select program is a game-changer for making money from rent in Vancouver. It offers up to 95 percent loan-to-value financing and amortization periods of up to 50 years. This can significantly reduce your payments and improve your cash flow. For example on a $10 million apartment building a 50-year amortization period can drop your debt service by 30 to 40 percent. This can be the difference between a property that loses money and one that makes money. To access the tier you need to score 100 points on CMHCs scale across affordability, energy efficiency and accessibility. It is not easy. For investors who can meet the requirements the rewards are substantial. Sustainable Real Estate Investing: The New Paradigm Investing in estate in Vancouver has changed from a speculative model to a long-term hold strategy. In 2026 investors need to be smarter than ever focusing on the fundamentals of yield and strategic location rather than just relying on the value of the property to go up. The investors who will succeed are those who prioritize making money from rent in Vancouver from the start. They are looking at properties where the numbers work without relying on price gains. They are taking advantage of opportunities in buildings. They are exploring markets where the prices are lower. They are using programs like MLI Select to improve their financing 10

Net Operating Income
Blog, Capital Investment

Net Operating Income vs Gross Operating Income: Which Metric Should Investors Trust?

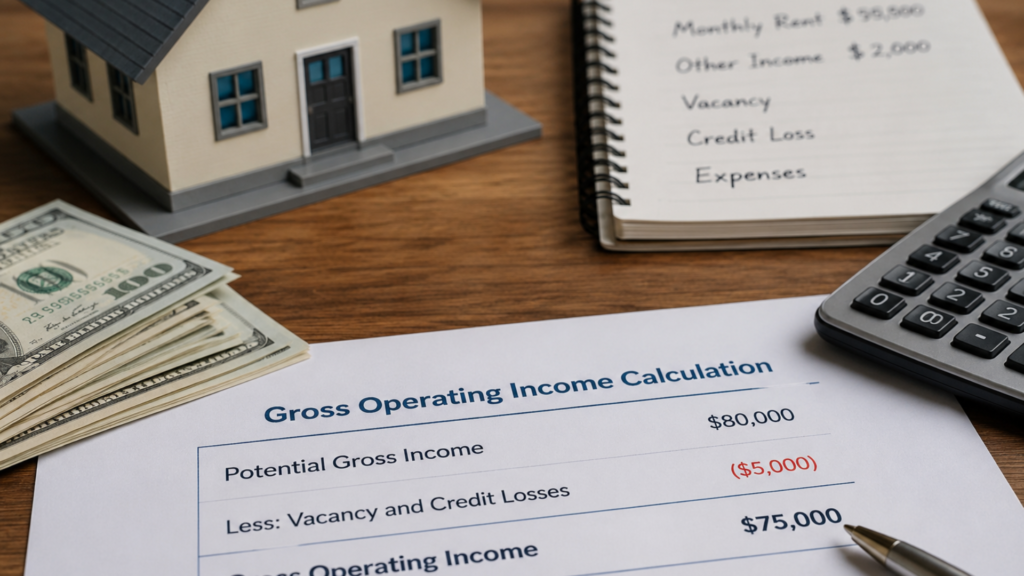
I have been in your shoes before looking at a property’s financials and feeling completely lost. There are a lot of numbers to look at. Two things you will hear a lot in real estate investing are gross operating income and net operating income in real estate. But here is the thing. They tell different stories about how a property is doing. If you mix them up you could lose money. Gross operating income is the money a property makes while net operating income in estate shows what is left after paying all the bills. In this guide, I will explain what each metric means, how to calculate them and which one you should trust when making investment decisions. By the end you will look at a property’s financials in a way. What Is Gross Operating Income? Let me start with the one. Gross operating income is the money a property makes from all sources minus the money lost to empty units and unpaid rent. Think of it as the money that actually goes into your bank account from the property before you pay any bills. To calculate operating income, you start with the money you would make if every unit were full and every tenant paid on time. Then you subtract the money lost to units and unpaid rent. The formula is: Gross Operating Income = Potential Gross Income- Vacancy and Credit Losses Here is an example. Imagine you own a six-unit building where each unit rents for $2,000 per month. The money you would make if every unit were full is $144,000 per year. But over the year you have one unit empty for two months. That is a loss of $4,000. And one tenant does not pay for a month. That is another $2,000 loss. Your gross operating income would be $144,000 minus $6,000 or $138,000. Gross operating income includes not rent, but also other money the property makes, like parking fees and laundry money. It shows how much money the property can make but it does not tell you if it is profitable. That is where net operating income in estate comes in. What Is Net Operating Income in Real Estate? If gross operating income is the money a property makes net operating income in estate is the money it keeps after paying all the bills. Net operating income in estate is calculated by subtracting all the bills from your gross operating income. The formula is simple: Net Operating Income = Gross Operating Income, Operating Expens But what counts as a bill? The government and real estate professionals include property taxes, insurance, management fees, maintenance and utilities. They do not include mortgage payments, income taxes and big purchases. This is an important difference. Net operating income in estate shows how profitable a property is before considering financing and taxes. Using our six-unit example lets say your annual bills are $42,000. Your net operating income in estate would be $138,000 minus $42,000 or $96,000. The Key Difference: What Each Metric Actually Tells You Here is the part. Gross operating income tells you how money a property can make. Net operating income in estate tells you how much money it actually keeps. Which one should you trust? You should trust both. For different reasons. Gross operating income is useful for comparing properties and understanding how money they can make. Net operating income in real estate is the metric that really matters for deciding if a property is a good investment. Lenders look at operating income in real estate to see if a property can pay its debts. Appraisers use operating income in real estate to determine a property’s value. Here is a scenario that shows why net operating income in estate matters more. Imagine two properties that make the amount of money. Property A has bills of $60,000 so its net operating income in estate is $90,000. Property B has bills of $100,000 so its net operating income in estate is $50,000. Both properties look the same at first. Property A is actually more profitable. If you only looked at operating income you would miss this important difference. The Income Approach to Valuation One of the important uses of net operating income in real estate is to determine a property’s value. The income approach to appraisal calculates a property’s value by dividing its operating income in real estate by a capitalization rate. The capitalization rate is the return on investment that investors expect based on market conditions and property risk. Here is how it works. If a property makes $100,000 in operating income in real estate and the capitalization rate is 5% the property’s value would be $2,000,000. This is why investors focus much on net operating income in real estate. It directly affects a property’s value. Which Metric Should Investors Trust? If you are thinking about investing in a property you should look at operating income in real estate. It is the metric that lenders use to decide if a property is a risk the metric that appraisers use to value properties and the metric that shows if a property can actually make money. Do not ignore gross operating income completely. It is useful for understanding how money a property can make and for comparing properties. A low gross operating income might mean that a property is not making much money as it could be. The real takeaway is this: gross operating income is the starting point but net operating income in estate is the important one. One shows you the money coming in the other shows you the money you actually get to keep. Understanding the difference between operating income and net operating income in real estate is important for any real estate investor. Gross operating income shows how money a property can make while net operating income in real estate shows how much money it actually keeps. Both are important. Net operating income in real estate is the one that really matters for investment 10

Capital Investment

Why Energy Efficiency Is the Investment You Are Probably Overlooking

Let me ask you something: when was the last time you thought about your buildings energy performance as a financial asset rather than just an operating expense? If you are like investors I talk to, probably never. Here is the reality that is reshaping modern real estate. Energy efficiency has evolved from a nice-to-have environmental feature into a hard nosed financial strategy that directly impacts your bottom line. Whether you are a developer planning a multifamily project or an investor holding an aging commercial property energy efficiency is now the single most underutilized lever for boosting returns lowering risk and securing better financing. In this guide we will explore why energy efficiency deserves a place in your investment thesis and how you can start capturing its benefits today. The Financial Case for Energy Efficiency Let us cut through the rhetoric and talk about real money. The numbers behind energy efficiency are compelling enough to make any investor sit up and take notice. Studies show that every dollar invested in energy efficiency can yield returns of three dollars to five dollars over the life of the investment. That is a return profile that would make most Wall Street funds envious. The benefits go far beyond simple payback calculations. Energy efficiency directly reduces one of your most unpredictable operating expenses: utility costs. Electricity expenses alone can account for four percent to twenty six percent of a buildings value. When you improve energy efficiency through HVAC systems, enhanced insulation and smarter building controls you are not just saving money. You are insulating your investment from volatile energy prices and carbon taxes that are only going to rise. Consider this: a near zero energy building can achieve a forty seven point six percent reduction in costs compared to a conventional building. That is not an improvement. That is a transformation of your propertys financial profile. Lower operating costs mean net operating income, which directly translates to higher property values and better cap rates. Energy Efficiency and Property Values: The Green Premium Here is something I find fascinating: the market is actually paying a premium for energy efficiency now. Green-certified buildings consistently command higher rents and sale prices than their less efficient counterparts. Research shows that energy efficient properties can achieve rent and sale premiums of four percent to ten percent compared to properties. In some markets highly energy efficient assets command up to seven percent higher rents, forty five basis points lower yields and five percent less vacancy. What is driving this premium? Tenants are increasingly prioritizing energy efficiency in their leasing decisions because it directly reduces their operating costs. They are willing to pay more for a space that will save them money on utilities month after month. As one industry observer noted, energy efficient buildings powered by reliable energy are increasingly viewed as sources of competitive advantage. Offering improved operating performance reduced exposure to energy market volatility and stronger tenant and investor appeal. The market is also penalizing the opposite. There is a growing discount where properties with outdated inefficient systems are being punished with lower valuations and reduced liquidity. In words failing to invest in energy efficiency is not just missing an opportunity. It is actively eroding your assets value. The Financing Advantage: How Energy Efficiency Unlocks Terms This is where energy efficiency gets really exciting from an investors perspective. Governments and lenders are now offering financial incentives for energy efficient buildings and these incentives can completely transform a projects economics. In Canada the CMHCs MLI Select program is perhaps the powerful example. This program rewards multi unit projects for achieving energy efficiency, affordability and accessibility targets. Projects that earn points unlock premium discounts of up to thirty percent on mortgage insurance extended amortization periods of up to fifty years and loan to value ratios as high as ninety five percent. Let me put that in dollar terms. On a ten million dollar project the difference between scoring fifty points and one hundred points in the MLI Select program can save you roughly one hundred sixty thousand dollars to one hundred eighty thousand dollars in mortgage insurance costs alone. The extended amortization at one hundred points can drop your debt service by eight percent to twelve percent compared to the forty year term available at fifty points. That is money that goes straight to your bottom line. The best part? Energy efficiency alone can get you a portion of the way there. Projects that achieve a forty percent improvement over building code energy performance can earn the fifty points available in the energy category. Even a twenty percent improvement earns twenty points, which combined with categories can push you into the enhanced financing tiers. Future Proofing Against Regulation and Risk Here is another reason energy efficiency deserves your attention: regulation is coming. Building codes are getting stricter, carbon taxes are rising and minimum energy performance standards are being implemented in jurisdictions. Buildings that do not meet these standards will face penalties, higher operating costs and potentially even restrictions on use. Investing in energy efficiency Investing in energy efficiency now is a form of risk management. As one analysis put it structures designed to be more resilient and energy efficient are better prepared for weather and to comply with future building code and updated regulation. You can. Invest proactively in energy efficiency on your own terms or you can be forced to do it later under less favorable conditions. The market is already signaling this shift. A twenty twenty five JLL survey found that seventy six percent of investors now factor sustainability into their real estate decisions. In Asia Pacific forty four percent of investors demand energy efficiency as a negotiable criterion. These trends are only. Properties that lag on energy efficiency will find themselves increasingly marginalized. Practical Steps to Capture the Energy Efficiency Opportunity So how do you actually start capturing these benefits? Here is what I recommend: For construction: Design for energy efficiency from the start. Work with an 10

Down payment
Blog, Capital Investment, Real Estate

Zero Down Payment Options That Actually Work in Canada

You have been saving your money for a time. You found a home you really like. The down payment is still a little out of reach. What if I told you that you might be able to get some money that you did not even know was available to you? As a property management company in Calgary Green Casa has helped a lot of renters find out about home buying grants and loan options that they did not know about. Today I am going to tell you about some programs that people often overlook. You will learn about loans with no interest, tax withdrawals and shared equity programs. By the end of this you will see ways to buy a home that your lender probably did not tell you about. The Home Buyers Plan Is More Than Withdrawing Money From Your RRSP Most people know that the Home Buyers Plan lets you take out $35,000 from your RRSP without paying tax. Here is something you might not know. If you have a spouse or partner, they can also take out $35,000 from their RRSP. That is a total of $70,000. You do not have to pay back the money for two years. Then you have 15 years to pay it back. If you miss a payment, that amount gets added to your income for that year. Here is a strategy that a lot of first-time buyers do not know about. You can put money into your RRSP today. Take it out under the Home Buyers Plan in as little as 90 days. The money you put into your RRSP gives you a tax refund, which you can then add to your payment. This is like getting money from your tax refund. Among all the home-buying assistance programs, the Home Buyers Plan is one of the most flexible. The First Time Home Buyer Incentive Is Like Having The Government As Your Partner Have you heard of equity? The government has a program called the First-Time Home Buyer Incentive, which gives you 5 or 10 percent of the price of the home you are buying. If you are buying a resale home you get 5 percent. If you are buying a home you get 10 percent. You do not pay any interest on this money. You pay back the incentive when you sell the home or after 25 years. You pay back the percentage of the homes value at that time. So if the government gave you $20,000 for a $400,000 home and later you sell it for $500,000 you pay back 5 percent of $500,000 which’s $25,000. Yes you pay back more if the homes value goes up. You also pay back less if the homes value goes down. This is not a loan. It is a shared equity program with no payments. The Alberta Down Payment Assistance Program The government of Alberta wants you to buy a home. Through the Alberta First Time Home Buyer Program you can get a loan of up to 10 percent of the price of the home up to a maximum of $40,000. This loan has no interest for the five years. After five years the interest rate is prime minus one percent. You must have a household income under $120,000. You must buy a home that costs than $400,000. The home must be your residence for least four years. This program is for buyers with credit and stable jobs who cannot quickly save for a down payment. As a property management company in Calgary we have seen this program help renters become owners in neighborhoods like Marlborough, Forest Lawn and Ogden. CMHC First Time Home Buyer Mortgage Loan Insurance You have probably heard of CMHC insurance. Did you know that CMHC also gives refunds to first-time buyers? If you buy an energy- home or a home in a designated revitalization area you can get a refund of up to 25 percent of your mortgage insurance premium. For example on a $400,000 home with 5 percent down your CMHC premium is about $15,200. A 25 percent refund puts $3,800 back in your pocket. You also have the option to add your CMHC premium to your mortgage or pay it upfront. This reduces the cash you need to pay at closing. Many buyers do not realize that mortgage insurance is not a penalty. It is a tool that lets you buy a home with than 20 percent down. The GST New Housing Rebate For Buyers If you buy a home you pay GST. The government gives you a rebate of 36 percent of the GST you paid up to a maximum of $6,300. For homes that cost than $350,000 you get the full rebate. For homes that cost between $350,000 and $450,000 the rebate gets smaller. For homes that cost than $450,000 there is no rebate. The builder often applies this rebate directly when you close the deal so you never pay the GST upfront. This lowers the price of a home by thousands of dollars. For buyers looking at condo developments in Calgary communities like Seton, Evanston or Walden this rebate can be the difference between affording the home or not. Why Alberta Has An Advantage Over Other Provinces Here is a benefit for buyers in Calgary compared to Ontario and BC. Alberta does not have a land transfer tax on home purchases. You only pay a fee of about $50 to $200 for title registration. In Toronto or Vancouver buyers can pay $10,000 to $20,000 in land transfer taxes. That money can go towards your payment moving costs or new furniture instead. So while this is not a grant or a loan it is a saving that makes Calgary one of the affordable major cities for buyers. When people ask me why they should buy in Calgary of Toronto I start with this. How To Combine These Hidden Programs For Maximum Benefit It is about strategy. Imagine you are buying a $380,000 townhouse 10

Scroll to Top

Compare