Green Casa Commercial

Get In Touch

Green Casa Popup Form

CMHC MLI Select

Here you can find in-depth information about the CMHC MLI Select program, with everything you need to better understand it and make the process simpler.

CMHC MLI Select apartment investing in Alberta
Blog, CMHC MLI Select

How MLI Select is Supercharging Apartment Investing in Alberta

The Alberta rental market is full of opportunity, but also full of challenges. Between rising interest rates, tighter financing rules, and higher construction costs, multi-family investors need more than just a good deal to succeed. They need smart financing that works for them, not against them. That’s why more and more apartment investors in Alberta are turning to CMHC’s MLI Select program. It’s not just financing. It’s a strategy. Why MLI Select Matters More Than Ever Alberta’s urban centers, like Calgary and Edmonton, are seeing strong demand for rental housing. With population growth outpacing new construction in many areas, the fundamentals are solid. But many investors are stuck, unable to scale because their capital is tied up, or their cash flow is too tight. MLI Select solves both problems at once. Top Benefits of Using CMHC MLI Select 1. You Keep More of Your Capital One of the biggest barriers to scaling your portfolio is capital. Under traditional financing, you might need 20 to 35 percent down. That adds up quickly. MLI Select allows qualified properties to be financed at up to 95 percent Loan-to-Value. That means you only need 5 percent down, freeing up cash for renovations, operating reserves, or additional acquisitions. It’s not just about buying a property. It’s about growing your business. 2. Get the Best Cash Flow of Your Life With up to 50-year amortization, your monthly mortgage payments are significantly reduced. That means: More money stays in your pocket each month You’re better positioned to ride out vacancies or unexpected costs Your properties become easier to manage financially Especially in Alberta’s variable economy, having predictable and healthy cash flow gives you a serious advantage. 3. Your Portfolio Grows Faster and Safer If you can buy more properties with less money down and keep each one cash-flowing, then you can grow much faster without taking on excessive risk. MLI Select is particularly powerful for investors who already own one or two buildings and are looking to expand. By recycling capital and improving debt coverage, you can scale with confidence instead of hesitation. 4. You Get Rewarded for Doing Good MLI Select also includes built-in incentives for properties that are energy efficient, accessible, or offer affordable units. For example: Install high-efficiency HVAC systems or insulation upgrades Include units that are wheelchair accessible Keep a percentage of your units below market rent By doing so, you can qualify for more favourable terms, which can include higher LTVs, better amortization, or reduced premiums. It’s good for your bottom line and good for your community. 5. Alberta is the Perfect Market for MLI Select Why Alberta? Because demand is high, taxes are low, and the rental market continues to strengthen. Cities like Calgary and Edmonton are seeing population growth and rising rents, but financing remains a challenge for many. That’s why CMHC’s MLI Select program is gaining traction here. It gives investors the edge they need to keep moving forward even in uncertain economic times.   Conclusion MLI Select isn’t a shortcut. It’s a smart, strategic tool for apartment investors who want to grow sustainably and profitably in Alberta’s evolving rental market. Whether you’re looking to acquire your first 12-unit or scale into your third 50-unit, CMHC’s MLI Select program can help you borrow more, spend less, and grow faster, all while building a better future for your tenants and your bottom line. Frequently Asked Questions (FAQs) What is the CMHC MLI Select program? CMHC MLI Select is a financing program designed to support rental housing projects that meet specific affordability, accessibility, and energy efficiency criteria.   How can CMHC MLI Select benefit apartment investors in Alberta? It can help eligible investors access favourable financing terms, preserve more capital, and improve the financial flexibility of multi-family rental investments.   What types of properties can qualify for MLI Select? Eligible multi-family rental properties may qualify when they meet CMHC requirements related to affordability, energy efficiency, accessibility, and other program criteria.   Can MLI Select help investors grow their rental portfolio? Yes. By potentially reducing the amount of capital required upfront and offering longer amortization options, the program can give qualified investors more flexibility to pursue additional acquisitions.   Does MLI Select support affordable rental housing? Yes. Affordability is one of the areas recognized under MLI Select, alongside energy efficiency and accessibility. The specific requirements depend on the project and financing application. Hafil Perincheeri Co-Founder & Director Linkedin Envelope Instagram Hafil Perincheeri is an engineer-turned-realtor, investor, and builder based in Calgary, Canada. As Co-Founder and Director of Greencasa, he specializes in home flips, property development, and investment strategies. Since 2019, he has guided clients in home buying, multifamily investing, and financing options like CMHC and MLI Select, ensuring transparent, informed decisions. Get A Free Quote Green Casa Contact Form Full NamePhone NumberEmailCityServices– Select –Property ManagementConstruction ConsultancyCapital InvestmentMLI Select Program GuidanceDescribe your Requirement:Submit
MLI Select
Blog, CMHC MLI Select

The MLI Select Readiness Check: Find Out If Your Project Qualifies Before You Apply

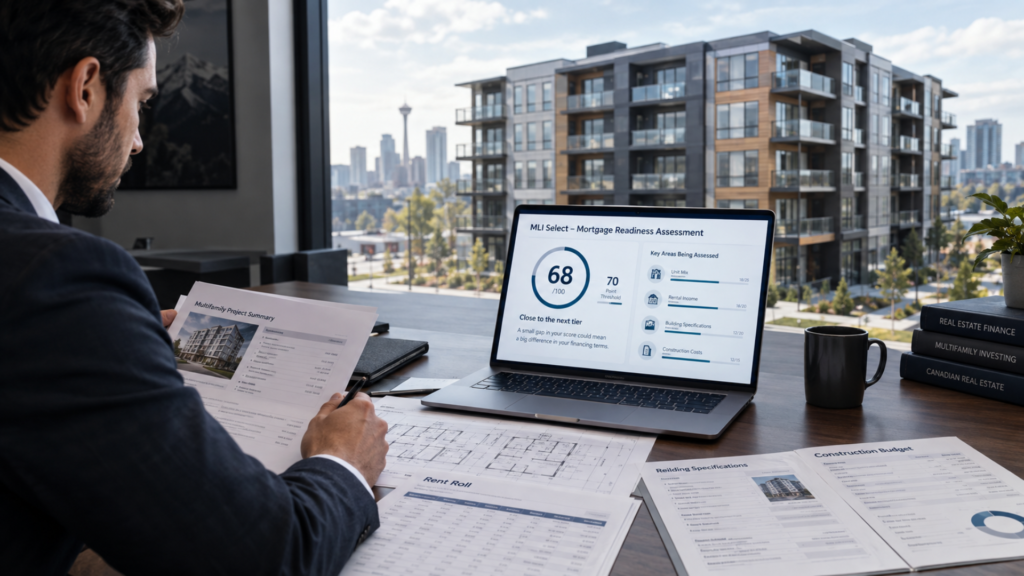
You have heard the numbers. Up to 95% financing. Amortizations that can last 50 years. Premium discounts that can save six figures. Here is the question that actually matters: does your project qualify for MLI Select? I have watched many investors spend months putting together an application only to find out they are 15 points short of the tier they were hoping for. That is why a free MLI Select readiness assessment is important. Before you put time, money and energy into an application, you deserve an answer about where your project really stands. In this guide, I will walk you through what a readiness assessment covers, the factors that determine eligibility and how to find out quickly whether your project is ready to move forward. Why You Need a Readiness Assessment Before You Apply Let me be straightforward with you. MLI Select is not a program you can figure out as you go. The scoring is strict in one way: it is all or nothing at the tier thresholds. A project that scores 68 points does not get credit for 70-point benefits; it drops to the 50-point tier. That gap can be the difference between a 45-year amortization and a 40-year one or between a 20% premium discount and a 10% one. A readiness assessment exists to find those gaps before your lender submits. We look at your unit mix, your rent roll, your building specifications, and your construction budget. Then we tell you clearly which points you can realistically claim, which ones need work, and whether the tier you want is actually possible. That conversation usually takes less than a week. The application process takes months. Getting the order right saves you money. The Three Point Categories You Need to Score To understand readiness you need to understand what you are being scored on. MLI Select gives points across three categories. The minimum requirement is 50 points. Affordability Points This is the powerful tool and the only category that can reach 100 points alone. You earn points by committing a percentage of units to rents at or below CMHC’s affordability threshold for your market. Forty percent of units gets you to 50 points. Sixty percent gets you to 70. Eighty percent gets you to 100. A 20-year commitment of 10 adds bonus points on top. For projects, affordability is where the score is won or lost. Energy Efficiency Points Energy points reward buildings that exceed performance. A 15% reduction in energy use earns 20 points. A 25% reduction earns 35 points. A 40% reduction earns 50 points. This category needs third-party modelling and an energy advisor’s confirmation, so you need to know if your design can actually reach those targets. Accessibility Points Accessibility points reward buildings that’re barrier-free and visitable. Every building must be 100% visitable as a baseline before any accessibility points count. From there, 15% accessible units can earn 20 points, and universal design across all units can earn 30. The September 30, 2026 Deadline Changes Everything Here is the part that makes a readiness assessment urgent of just helpful. CMHC is changing the energy baseline. Until September 30 2026 applications can be scored based on the 2015 National Building Code and 2017 National Energy Code. After that date, everything is scored based on the 2020 codes. What does that mean in life? A project that comfortably earns 35 energy points today might earn 20 under the new standards, with the same building envelope. If you are at 70 points and relying on energy to get that shift could push you down to the 50-point tier. If you are at 100 points you might fall to 70. We have seen this happen already. Investors who assumed their design would score the same under either code have been surprised. A readiness assessment tells you which baseline you should use and whether you need to move What We Actually Review During Your Assessment When you ask for a free MLI Select readiness assessment, here is what we look at together. We review your forma and rent roll to find out which units could reasonably be considered affordable and how that affects your net operating income. We look at your building plans or built drawings to assess energy and accessibility potential. We check your unit mix. Confirm the non-residential part stays under the 30% limit. We check occupancy history for existing buildings; 85% occupied for 90+ days is a base requirement for acquisition or refinance. We map out which tier is realistic, which is a stretch, and which is out of reach. The goal is not to tell you what you want to hear. It is to give you a picture before you spend money on an application. Who Should Request an Assessment You should schedule a readiness assessment if you are building a building with five or more units, buying an existing multi-family property and thinking about MLI Select financing, refinancing a building you already own or converting a property into rental use. If you are unsure whether your project has five units or more or if your zoning allows the use you are planning that is the kind of question we can help with. We work with investors at every stage from first-time buyers looking at a six-plex to experienced developers with 50-unit portfolios. The assessment is free it is specific to your project. There is no need to proceed. The difference between an MLI Select application and a rejected one is not usually ambition; it is preparation. Knowing your score before you apply means you can fix gaps adjust commitments or choose a tier that actually works for your numbers. With the September 30 2026 energy code deadline coming up the cost of guessing is higher than ever. Request a free MLI Select readiness assessment today. Lets find out together if your project is ready. It takes more time than you think and it could save you six figures in financing costs. Frequently Asked Questions 10

MLI Select Compliance Checklist
Blog, CMHC MLI Select

The Paper Trail That Protects Your Financing: An MLI Select Compliance Checklist for Property Managers

Congratulations, you’ve completed the CMHC MLI Select application process and secured financing. But here’s the truth that surprises property owners: approval isn’t the end. It’s the start. MLI Select compliance tracking is a detailed job that property managers should take as seriously as the first application. In 2026, CMHC has made enforcement of MLI Select rules stricter. The consequences of not following the rules are serious: if a borrower doesn’t respond or can’t fix the problem, the results can now include being not allowed to use MLI Select for at least five years. In this guide I will show you a MLI Select compliance checklist, what property managers need to keep track of after approval how to show that you are following the rules and what to do before the September 30 2026 energy code deadline. Understanding the Three Phases of MLI Select Verification Before we get into the checklist, let me explain the three steps of the verification process from CMHC. Phase 1. Pre-Approval: is when you list your promises before getting the insurance letter. Phase 2. Post-Construction/Acquisition: is when you check that the promises you made were actually done. Phase 3. Compliance: is the yearly reports that show that the promises about affordability are still being kept, usually for 10 to 20 years. The first two steps are behind you. It is Phase 3 that needs MLI Select compliance tracking every year. Affordability Compliance: The Important Duty Affordability is the part that needs the most attention. When you said you would follow the affordability rules, you signed an Affordability Commitment Letter that said exactly how many units, the rent that is allowed, and the minimum period of 10 years. That promise is legally required. Here is what MLI Select compliance tracking for affordability requires on a basis: Annual Rent Reporting You have to give yearly reports about the rent you charge for the affordable units. Papers must show that the units are lived in by people paying at or below the rent that is allowed. CMHC publishes rent numbers adjusted for inflation that you must use. Lease Papers For buying buildings, you need the lease papers showing the rent for all the units that are occupied. For compliance, you need the signed leases for the affordable units that show you are doing what you promised. Affordability Monitoring Plan CMHC needs a written plan showing how you will keep track of and report affordability each year. This is not a choice; it is a must for the program. Key Rule: You have to give the papers about compliance to CMHC through your lender during the 10-year affordability period. You can’t send them directly; you go through your lender. Energy Efficiency Compliance: Checking and Watching Performance Energy efficiency compliance has two main parts: checking after the building is done and keeping track over time. Post-Construction Check For buildings, CMHC needs a check after construction to make sure that the energy features were built as promised. This includes an EnerGuide as-built evaluation done by a certified energy advisor, including a test to see how well the building holds air to make sure the real performance matches the promise. For buildings, you need to check after a retrofit by doing another energy check. Final papers must be sent to CMHC through your lender before the mortgage is fully given. Ongoing Energy Watch Once it is checked, the energy efficiency points are usually. Don’t need yearly reports. Property managers should still watch the real energy use compared to the expected amount. Big differences could mean problems that affect the tenants and the building. Papers Needed For buildings, you need the EnerGuide energy model report from the design phase the blueprints that show the details, and the summary from the mechanical engineer. For buildings, you need the energy check before the retrofit, the plan for the retrofit the report from the energy modeler, and the quotes or contracts from the people doing the work. Accessibility Compliance: Permanent Features, Permanent Papers Accessibility features are parts of the building; they don’t need yearly reports like affordability does. They do need the right papers: Post-Construction Check CMHC might ask for a statement from your architect or a visit to the site to make sure that the accessibility features are there and correct. This confirms that the units are easy to get into the layouts can be. The design is fair. Papers to Keep Keep the blueprints with the accessibility features marked. Keep the architect’s statement or the site check report. These papers should be kept in case CMHC checks them again. What Makes a Score Checked Again MLI Select compliance tracking is very important when certain things happen that make the score checked again. CMHC may check a project’s score in three cases: Big Change in Design During Building If the energy or accessibility features you said you would use during the application are changed during building the final check might show a different score. Real Energy Performance is Lower Than Expected If the EnerGuide check shows that the building is not as good as it was supposed to be, CMHC might change the score. Maybe move the project to a lower level. Not Meeting the Affordability Promise If the yearly reports about affordability show that some units are rented for more than the allowed amount CMHC can take action including changing the insurance rules. The September 30, 2026 Deadline There is a date that every MLI Select property manager should remember. On November 28 2025 CMHC updated the MLI Select rules. There is time to get ready until September 30 2026. Before that date CMHC will take applications based on the 2015/2017 energy rules OR the new 2020 rules. After that date only the new 2020 rules are allowed. The 2020 NECB and 2020 NBC houses are more efficient. A project that got 50 points with the rules might only get 35 points with the new ones. For buildings the rules you used before the 10

MLI Select refinancing
CMHC MLI Select

Navigating the 2026 CMHC Rule Changes: Refinancing Existing Rentals with MLI Select

Have you ever looked at your apartment building. Wondered if you could get better loan terms than the ones you signed years ago? I have been in that spot. The good news is that MLI Select refinancing existing buildings is not a dream, it is one of the smartest moves you can make as a multi-family investor in 2026. Many owners think the CMHC MLI Select program is for new buildings. That is not true all. CMHC built MLI Select to help with building construction buying buildings or MLI Select refinancing existing buildings. In this guide I will show you how MLI Select refinancing existing buildings works what you need to qualify and why you should watch out for the September 30 2026 energy deadline. Can You Really Refinance an Existing Building with MLI Select? Let me answer the question you are probably thinking now: yes you really can. MLI Select refinancing existing buildings is an popular way for multi-family owners in Canada to manage their properties. This program works for builds buying buildings and MLI Select refinancing existing buildings. The program also supports the refinancing of existing properties. If you have a loan on an apartment building right now you can move that loan into an MLI Select insured mortgage if your property meets the rules. The main thing to remember is that you must apply for a CMHC-insured loan through a refinance. You cannot just change your mortgage to MLI Select terms without doing a full refinance. This part is important. MLI Select refinancing existing buildings means you have to go through the application process with a lender just like when you buy a new place.. Once you get the green light the perks are huge. You can get up to 95% loan-to-value pay the loan over up to 50 years and get discounts on premiums of up to 30%. What Properties Qualify for MLI Select Refinancing? The point system is where MLI Select refinancing existing buildings gets interesting. Since you are not building from scratch you cannot change everything. You have to work with what you have like the walls, the pipes and the layout of the building. Affordability Points: The Primary Lever Affordability is often the way to get points for existing buildings. You do not have to change the building all. You just have to promise to rent a number of units at or below the rent levels set by CMHC for the Calgary CMA for at least 10 years. Here is how it works: if 40% of units are at 30% of the renter income you get 50 points. If it is 60% you get 70 points. If it is 80% you get 100 points. If you commit to 20 years of affordability you get more bonus points. The great thing about MLI Select refinancing existing buildings is that you can plan this around when tenants move out naturally. This way you do not have to kick anyone out. If your building already has some units you can just officially commit to them. Energy Efficiency Points: Retrofit Pathways You earn energy efficiency points for existing buildings by showing that you reduced energy use compared to how much you used. CMHC needs an energy auditor to check your starting point and your goals. The cheapest ways to upgrade existing family buildings usually involve things like swapping old gas boilers for new efficient ones putting LED lights in halls sealing air leaks or adding smart thermostats. These upgrades usually cost between $1,500 and $2,500 per unit. You can earn points at three levels: a 15% drop in energy gets 20 points a 25% drop gets 35 points. A 40% drop gets the full 50 points. Accessibility Points: Retrofit Feasibility Making an existing building can be easy or very hard depending on how old the building is and how it was built. Easy jobs include adding parking, automatic door openers or better signs. Medium jobs include adding grab bars in bathrooms or widening doors if the walls are easy to move. These upgrades can cost between $5,000 and $15,000 per unit. The September 30 2026 Deadline: What You Need to Know There is a date that every investor needs to remember. On November 28 2025 CMHC changed some rules for the MLI Select program. There is a transition period that lasts until September 30 2026. Until that day CMHC will let you use the energy rules or the new 2020 codes. After that date you must use the 2020 codes. The new 2020 codes are much stricter. A project that easily gets 50 points using the rules might only get 35 points under the new ones. This gives you a window of time. If your building can get points using the easier rules you should lock that in before the deadline hits. The Refinancing Process So what does the actual work look like for MLI Select refinancing existing buildings? First find a lender that knows how to do MLI Select financing. Then make a plan to get your points. Find the way to hit 50 points, usually that starts with affordability, then energy, then accessibility. Next write everything down. For energy you will need an auditor. For affordability you will need to show your rent plans. Finally send it to your lender. It usually takes about 60 to 90 days to get approved. Once you are approved you get all the benefits. MLI Select refinancing existing buildings is a way for owners to get better loan terms lower their monthly bills and find more cash for other deals. With up to 95% LTV 50-year terms and big discounts on premiums this program can change how your building makes money. The September 30 2026 deadline means you should act fast. If your building fits the energy rules you can get those points easily. Without energy upgrades just promising lower rents can get you 50 points. Your building might be able to get better terms than you think. 10

Applying MLI Select
CMHC MLI Select

What Investors Need to Know About Applying MLI Select to Existing Buildings

Have you ever heard someone say that MLI Select financing is only possible for an existing building if a major renovation is being done? I have heard that claim too. It is simply not true. The reality is that MLI Select can be applied retroactively to existing buildings. There is a catch. MLI Select benefits cannot be applied to a mortgage without refinancing. The program is available for construction, purchases and refinances of existing buildings. In this guide I will walk you through what “retroactive” means in practice how to structure a refinance that qualifies and the strategic considerations for existing building owners. What “Retroactive” Actually Means in Practice Let me clear up the confusion. When people ask about “retroactive” MLI Select they are usually wondering one of two things: Can I apply MLI Select benefits to my mortgage without refinancing? Can I earn points for improvements that I have already made? The answer to both questions is: not directly. MLI Select can be applied retroactively through a refinance. You cannot apply for MLI Select on an existing property that you already own unless you are applying for CMHC‑insured financing typically through a refinance. You cannot retroactively claim points for energy retrofits completed before your MLI Select application. However you can structure your refinance around energy upgrades that you plan to complete within CMHC’s specified timeframe after acquisition, within 24 months. This means that MLI Select can be applied retroactively in the sense that you can refinance an existing building and access the program’s benefits. The application and approval happen before the new financing is in place. The Refinance Strategy: How to Structure Your Deal If you want to access MLI Select on an existing building here is the path. First assess your building. What is its occupancy rate? What is your current NOI? What energy efficiency or accessibility features does it already have? Next identify your point pathway. Affordability is often the easiest; commit a percentage of units to below‑market rents. Energy efficiency and accessibility require improvements. Then develop a retrofit plan. For energy you will need an energy auditor to establish a pre‑retrofit baseline. For accessibility you will need a feasibility assessment. Finally, refinance through a lender. Work with a mortgage broker who understands MLI Select to structure your application. This two‑step verification process means that all energy retrofit commitments must be completed within CMHC’s specified timeframe after acquisition, within 24 months. In practice this means you can apply for MLI Select with a documented retrofit plan complete the work after closing and have the energy performance verified afterward. If you have already completed energy retrofits you cannot claim points for them retroactively.. You can plan new retrofits around your refinance. Points Opportunities for Existing Buildings Let me walk you through the opportunities for earning points on existing buildings because this is where MLI Select can be applied retroactively in the most practical sense. Affordability: The Path of Least Resistance Affordability points require no changes to the building. You simply commit to renting a percentage of units below market rent for ten years or more. 40 % Of units at 30 % of renter income = 50 points (entry‑level). 60 % Of units = 70 points (45‑year amortization). 80 % Of units = 100 points (50‑year amortization + 30 % premium discount). A 20‑year affordability commitment adds 30 bonus points. For existing buildings you can designate units for affordability commitments to minimize revenue impact. Buildings already renting units below the affordability threshold can formally commit those units. Energy Efficiency: Retrofit Planning Energy efficiency points are earned by documenting a percentage reduction in energy consumption to a measured pre‑retrofit baseline. You need an EnerGuide evaluation including blower door testing to confirm as‑built energy performance meets the committed score. The cost‑effective pathways are: boiler replacement, common area LED lighting, building envelope air sealing, suite‑level heat pump water heaters and smart thermostatic controls. Accessibility: Feasibility Assessment Accessibility retrofits on existing buildings range from straightforward to prohibitively expensive. High feasibility: parking, automatic door openers, improved signage. Feasibility: bathroom grab bars doorway widening in non‑load‑bearing walls. Low feasibility: elevator access to walk‑up buildings, reconfiguring unit layouts, modifications. The Premium Math: What You’re Actually Saving Let me show you why MLI Select can be applied retroactively to existing buildings is worth the effort. The premium discount structure is straightforward. 50 + Points = 10 % premium discount. 70 + Points = 20 % premium discount. 100 + Points = 30 % premium. 50‑Year amortization. On a $5 million 24‑unit building: Traditional MLI Standard premium at 3.35 % costs $167,500. MLI Select with 70 + points at 2.68 % costs $134,000. Immediate savings: $33,500. MLI Select with 100 + points at 2.35 % costs $117,500. Immediate savings: $50,000. Extending from 25 to 50 years reduces debt service by approximately $8,200, which is $98,400 annually in improved cash flow. The September 30  2026 Deadline For existing buildings the retrofit criteria you were using before the changes are still in place. The overhaul is for new construction. Until September 30  2026 CMHC accepts applications under either the new energy standards. After that date it is the 2020 codes only. A project that easily scores 50 points against the codes might only score 35 points against the new ones. The transition window means you can lock in energy targets if you act before the deadline. Conclusion MLI Select can be applied retroactively to existing buildings. Only through a refinance. You cannot claim points for completed retrofits without refinancing. You can structure your refinance around a retrofit plan commit to affordability targets and unlock premium discounts up to 30 % and amortization up to 50 years. With the September 30  2026 deadline approaching the window to qualify under energy standards is closing. If you own an existing building with 5 + units now is the time to explore whether you can unlock financing terms. Your building might be worth more than you think with the financing structure. Frequently Asked Questions (FAQs) Can I apply MLI Select to an existing building? MLI Select can be applied retroactively through a refinance. You 10

MLI Select Construction
Blog, CMHC MLI Select

MLI Select Construction: How to Protect Your Points, Financing & Timeline

 You have the land; you have the money ready. Your MLI Select commitment letter is in your hands. Now comes the part that keeps developers awake at night: the building phase. Managing construction under CMHC MLI Select is very different from a build. If you miss a goal change your plans without asking or fail to write down your progress you could lose your points. If you lose those points you lose your financing too. In this guide I will show you what managing construction under CMHC MLI Select looks like in real life. I will talk about bonding, how you get paid checking your work and that September 30 2026 energy code deadline. I want to help you keep your project on track and keep your money safe. Bonding – The Rule You Cannot Skip Before you pour any concrete you must deal with bonding. Under the MLI Select program CMHC usually asks for 50% labour/material bonding and 50% performance bonding on all building contracts. This rule is there to protect everyone. If your builder stops working or does a job the bond pays to fix the problem. If you are building something like 24 units or less you might not need bonding if you have good money and a good builder. For big builds bonding is the standard. CMHC does let you try things sometimes like a letter of credit or giving more collateral. However you cannot just skip it. When you are managing construction under CMHC MLI Select get your bonding plan ready before you start digging. You cannot fix this once you start building. The Draw Schedule – How You Get Paid When you use MLI Select for construction you do not get all the money once. You get paid in steps. This is called a draw schedule. You get bits of money as you finish parts of the building. A normal draw schedule looks like this: Finishing the foundation (15-20% of the money) Finishing the frame and roof (25-30%) Finishing the walls (20-25%) Finishing everything (25-30%). Usually, you ask for money a month. CMHC will look closely at the first and very last payments. If you have one builder CMHC checks if that builder is good for the money. If you have a project manager they check the teams like the concrete and plumbing teams. The best way to succeed while managing construction under CMHC MLI Select is to stay on your schedule. If you miss a step you miss your pay. That can stop your project. Plan your time well. Leave extra room for delays. Progress Monitoring – CMHC Is Watching Once you get your letter the hard work starts. CMHC might ask for reports every month, photos or even visits to the site. They want to see that you are building what you promised. If you are building something in Alberta, CMHC will check the building after it is done. They want to make sure the energy savings and easy access features are actually there. If what you built is not what you promised your score will drop. A lower score could mean you lose your 50-year loan terms. If you want to change the design you must ask CMHC first. Do not make changes that lower your points. CMHC can take away your deal if the building is too different from the plans. When you are managing construction under CMHC MLI Select treat your plans like they are perfect. You must ask before you change anything. Post-Construction Verification – Prove What You Built For buildings, you must prove what you built. CMHC requires an EnerGuide check to see if the building saves as much energy as you said it would. This is where many people run into trouble. Your paper plans might look great. If the real building does not save energy your points will go down. CMHC might also ask your architect to sign a paper or visit the site to make sure the building is easy for everyone to use. You must send these papers to your lender before you get your mortgage. Remember, if you change the energy or access parts while building your final score might be lower. If the EnerGuide check shows the building is not as good as the plan CMHC might lower your points and your loan terms. The September 30 2026 Deadline – Why You Must Act Fast There is one date you must remember: September 30 2026. After this date CMHC will not use the energy rules anymore. Every new project will have to follow stricter rules. If you are still planning your project time is running out. Projects already being built are okay. New projects need to be careful. What does this mean? Many projects will get energy points under the new rules. This could mean your loan term goes from 50 years down to 45 years. When you are managing construction under CMHC MLI Select keep this date in your mind. If you want the rules you need to apply before the deadline. Managing construction under CMHC MLI Select is a deal. From bonding and pay schedules to checking progress and final proof you have to watch every detail. The September 30 2026 deadline makes everything move faster. If you want the standards you need to act now. The reward is great. You can get up to 95% LTV a 50-year loan and big discounts.. These rewards require you to follow every rule perfectly. Plan well write everything down. Talk to your lender and CMHC all the time. Your money depends on it. Frequently Asked Questions (FAQs) What bonding does CMHC require for MLI Select construction? CMHC usually wants 50% labour/material and 50% performance bonding on contracts. They might allow things like letters of credit if you ask. How does the draw schedule work? You get money in steps as you finish parts like the foundation, the frame and the final build. Usually this happens once a month. What is 10

Mortgage Insurance
Blog, CMHC MLI Select

Mortgage Insurance Explained: Why It Matters for Your Calgary Investment

Have you ever thought about why some mortgage payments have a fee? That is because of mortgage insurance. Understanding what mortgage insurance is can save you a lot of money on your Calgary investment. In words mortgage insurance is a protection plan that helps the lender if you cannot make your mortgage payments. You need to have this insurance if your down payment is less than 20 percent of the purchase price. I will explain how mortgage insurance works, how much it costs and how it can help you buy a property in Calgary sooner. Let us learn about this part of real estate investing together. What Is Mortgage Insurance? Let me explain it in a simple way. Mortgage insurance is a plan that protects the lender, not you if you cannot make your mortgage payments. You need to have this insurance by law in Canada if you put down less than 20 percent of the purchase price. The insurance cost is calculated based on your mortgage amount. Is usually added to your mortgage. CMHC, Canada Mortgage and Housing Corporation is a known provider but Sagen and Canada Guaranty also offer similar coverage with the same premium rates. Think of it as a fee you pay to buy a property with a down payment. How Much Does Mortgage Insurance Actually Cost? Now let us look at the numbers. In 2026 the insurance cost depends on your payment: 5 percent down: 4.00 percent of the mortgage 10 percent down: 3.10 percent of the mortgage 15 percent down: 2.80 percent of the mortgage For example if you are buying a $400,000 property in Calgary with a 5 percent down payment which is $20,000 your mortgage amount would be $380,000. The mortgage insurance cost would be 4.00 percent of that which’s $15,200. This cost gets added to your mortgage so you would actually be borrowing $395,200 in total. While it may seem like a cost without mortgage insurance you would need $80,000 down instead of $20,000. That is the difference between investing and waiting years to save up. When Is Mortgage Insurance Required? Mortgage insurance is required in Canada for any property purchase with a down payment of less than 20 percent. This applies to purchases up to $1.5 million. For investment properties the rules are a bit different. If you are buying a property with less than 20 percent down you need insurance. However, many investors choose to put down 20 percent or more to avoid the insurance cost. The 2026 Changes: What’s Different This Year? In February 2026, there were changes to the Canadian mortgage insurance rules. The insurance premiums. There were restrictions on how rental income can be counted when qualifying for a mortgage. These changes make it harder to qualify for a mortgage with insurance. CMHC also increased the insurable purchase price to $1.5 million and expanded 30-year amortizations to all first-time homebuyers. If you are considering a Calgary investment property these changes affect both your qualification and your costs. How Mortgage Insurance Protects Your Investment While mortgage insurance protects the lender it also helps you. Without mortgage insurance lenders would require down payments making it hard for people to buy properties. By allowing you to buy with as little as 5 percent down insurance opens doors that would otherwise be closed. For investors this means you can use your money effectively. Of putting $80,000 in one property you could use that money to buy multiple properties with 5 percent down. Over time that is how you can grow your portfolio. Can You Avoid Paying Mortgage Insurance? If you want to avoid mortgage insurance you need to put down at least 20 percent of the purchase price. For a $400,000 property that is $80,000. While the upfront cost is higher, you will save on the insurance cost. Have lower monthly payments. If you are buying a property priced over $1.5 million mortgage insurance is not available so you will need the 20 percent down. For investors the best option is to put down just enough to avoid the insurance cost while still getting into the market. Understanding what mortgage insurance is is essential for any Calgary investor. It is the key to buying with a down payment and in 2026 the rules have changed in ways that affect both your costs and your qualification. The insurance cost ranges from 2.80 percent to 4.00 percent of your mortgage depending on your payment. While it may seem like a cost insurance opens doors that would otherwise be closed allowing you to build your portfolio with less money upfront. Frequently Asked Questions (FAQs) What is mortgage insurance? Mortgage insurance is a protection plan that helps the lender if you cannot make your mortgage payments. It is required when your down payment is less than 20 percent of the purchase price. How much does mortgage insurance cost in 2026? The cost depends on your down payment: 4.00 percent with 5 percent down, 3.10 percent with 10 percent down and 2.80 percent with 15 percent down. Is mortgage insurance required for investment properties? Yes, if you are buying with less than 20 percent down. However, many investors choose to put down 20 percent or more to avoid the insurance cost. What is the maximum insurable purchase price? The maximum insurable purchase price is $1.5 million. Properties over $1.5 million cannot be insured regardless of your payment. What changed with mortgage insurance in 2026? There were changes, including higher insurance premiums and restrictions on how rental income can be counted for qualification. Can I avoid paying mortgage insurance? Yes, by putting down at least 20 percent of the purchase price. For a $400,000 property that is $80,000. Green Casa Co-Founder & Director Linkedin Envelope Instagram Hafil Perincheeri is an engineer-turned-realtor, investor, and builder based in Calgary, Canada. As Co-Founder and Director of Greencasa, he specializes in home flips, property development, and investment strategies. Since 2019, he has guided clients in home buying, multifamily investing, 10

rental reset
CMHC MLI Select

How Investors Can Use MLI Select to Capitalize on Vancouver’s Rental Reset

Vancouvers rental market is really changing. You are not imagining things. For years people have been competing with each other to rent a place. The rents have been very high.. Now Vancouvers rental market is going through a big change. 24,000 New rental units will be available in the next two years. This means there will be a lot of places to rent and it will be harder for landlords to find tenants. The construction of buildings is happening very fast. In 2025 and 2026 many new buildings will be completed. This is making it harder for landlords to increase the rent. In fact the rent is going down. This is news for people who are looking for a place to rent. It is not good news for investors who own rental properties. The Numbers That Explain Everything Lets look at the numbers. The vacancy rate in Vancouver is now 3.7 percent. This is the highest it has been since 1988. A few years ago the vacancy rate was very low almost 0.9 percent. What changed? Well many new buildings have been. This has added a lot of new rental units to the market. Also fewer people are moving to Vancouver because of changes in immigration policies. In 2025 the population of British Columbia actually decreased by over 41,000 people. Because of this the rent in Vancouver has gone down by 9.2 percent. Landlords are trying to attract tenants by offering one to two months of rent. This is a change from just a few years ago. New rental buildings that were built during the pandemic are having a time finding tenants. David Venance of Cushman & Wakefield said, “This is a change after a period of very high demand it’s not a sign of a weak market”. The Supply Pipeline: What’s Coming and When Its good to know whats happening in the market. 24,000 New rental units will be available in the next two years. Most of these are apartment buildings and many of them are in expensive areas. The Canada Mortgage and Housing Corporation says that the vacancy rate is highest in buildings, where landlords are offering incentives to attract tenants. It may take a years for the market to absorb all the new units and its unlikely that the rent will go up until 2028. There’s good news for investors. The number of buildings being constructed is going down. This means that in the future there will be fewer new rental units available. When people start moving to Vancouver the market may change quickly. Greg Ambrose of Colliers Canada said, “In two years we may be surprised by how the rental market changes with fewer new buildings and possibly new government policies to increase the population”. The Divergence: New Buildings vs. Legacy Assets One important thing to note is that new buildings and old buildings are doing differently in the market. New buildings are having a time finding tenants. Investors are being careful. Want higher returns on their investment. The value of buildings is going down and some sellers are having to borrow a lot of money to buy them. On the hand old buildings are doing better. The Canada Mortgage and Housing Corporation says that the market is still strong for buildings, especially the ones with low rent. Tenants are looking for deals and old buildings offer that. When you’re thinking of investing in the market this is an important thing to consider. New buildings may have amenities but they’re having a hard time finding tenants. Old buildings may not have all the amenities. They’re more stable and offer a better return on investment. Why This Is a Buyers Market For investors this change in the market is an opportunity. “For investors it’s now a buyers market in an asset class that has traditionally favoured sellers ” Ambrose said. What does this mean? There are buildings for sale and sellers have to compete with each other on price. Investors can get a deal and the return on investment is higher. Most of the buyers are investors and they’re being careful and disciplined. They’re finding deals that weren’t available a few years ago. The MLI Select Advantage for Multi-Family Investors If you’re looking at buildings with five or more units the Canada Mortgage and Housing Corporation has a program called MLI Select. This program offers financing terms that can change the economics of investing in rental properties. You can borrow up to 95 percent of the price. You can pay back the loan over 50 years. The interest rate is around 4.25 to 5.00 percent, which’s lower than other loans. To get the deal you need to score 100 points on the Canada Mortgage and Housing Corporations scale. You can get points for making the building more affordable energy-efficient and accessible. For investors who are buying buildings MLI Select can help improve cash flow and reduce the amount of money you need to invest. In a market where every dollar counts this program can make a difference. Where the Opportunities Are Based on whats happening in the market here are the opportunities for investors. Buildings that need renovation and have low rent offer a chance to make money. For example The Maples, a 38-unit building in Marpole has rent thats 23.51 percent below market. By renovating the units and increasing the rent investors can increase their income and the value of the property. Old buildings in locations are more stable than new construction and offer immediate cash flow. The suburbs like Surrey offer cash flow and lower prices. Other areas, like Burnaby, Coquitlam and Langley offer opportunities with potential for renovation and strong demand for rent. Purpose-built rental projects with MLI Select financing can change the economics of investing in properties. Conclusion Vancouvers rental market is going through a change. 24,000 New units, a 3.7 percent vacancy rate and falling rent have made it easier for people to find a place to rent.. For investors who 10

CMHC MLI Select
Blog, CMHC MLI Select

CMHC MLI Select in 2026: The Financing Tool Thats Transforming Multi-Family Investing in Alberta

I often wonder how some people buy apartment buildings with little money down. The answer is usually the CMHC MLI Select program. If you want to invest in -family homes in Alberta you need to understand this program. It is the important tool for buying or building rental properties in Canada right now. You can buy a property with little as 5 percent equity. In this guide I will explain how MLI Select works in 2026 what the recent changes mean for you and how you can use this program to grow your portfolio. Whether you are an investor or have experience this is information you cannot ignore. What CMHC MLI Select Actually Is Let me explain what CMHC MLI Select is. CMHC does not lend you money directly. A bank or credit union gives you the mortgage and CMHC insures the loan. Because the loan is backed by the government the lender takes on risk. They offer terms, such as higher leverage, longer amortization and lower interest rates. You pay CMHC a premium. The deal becomes cheaper and more forgiving. MLI Select replaced the MLI Flex product in March 2022. It has a points system on top of the insurance. The premium is a percentage of the insured loan. Is usually added to the mortgage. For anyone who wants to invest in -family homes understanding this program is crucial. The Points System: How MLI Select Rewards Better Buildings This is where things get interesting. Every MLI Select project gets points in three categories: affordability, energy efficiency and accessibility. You do not have to meet all three categories. You can focus on one. Combine them to get more points. The points you get the better your financing terms become. For affordability you get points by keeping some units at rents below the median market rent for at least 10 years. If you commit to 20 years you get 30 bonus points. For energy efficiency you get points by building or retrofitting to exceed baseline energy performance standards. For accessibility you get points by building barrier- units. The minimum required score is now 50 points. The Three Tiers: What Each Level Unlocks The points you get determine which tier you qualify for. Each tier unlocks financing. If you get 50 points you can get a 40-year amortization and a 10 percent premium discount. If you get 70 points you can get 45 years and 20 percent off. If you get 100 points you can get a 50-year amortization, up to 95 percent financing and 30 percent off the premium. Let me explain what this means. A 50-year amortization means monthly payments, which makes it easier to qualify for financing. Up to 95 percent financing means you can buy a building with little as 5 percent down. For projects up to $5 million you can put down little as 5 percent. These terms make MLI Select more accessible than commercial financing options. Why Alberta Is the Perfect Market for MLI Select Alberta has advantages that make MLI Select attractive. First there is no rent control. This means you can adjust rents to market rate when units are empty. If market rents increase 5 to 7 percent annually your rental income can increase at that rate. Second Albertas population is growing rapidly. Edmonton and Calgary are expected to grow by 2035. This growth means more people will need properties. The September 30 2026 Deadline: What You Need to Know There is a date to remember: September 30 2026. CMHC announced changes to MLI Select in November 2025. After September 30 2026 new applications will be scored against the 2020 National Building Code and 2017 National Energy Code. This means it will be harder to get points for energy efficiency. Projects that would have qualified for financing under the old rules might not qualify under the new rules. For investors this deadline creates both urgency and opportunity. Projects that qualify under the rules can lock in better terms. How MLI Select Is Reshaping Albertas Rental Supply MLI Select has been responsible for a portion of multi-family new construction in Canada. The program offers interest rates reducing borrowing costs for multi-unit residential property construction, purchase and refinancing. It offers premiums and longer amortization periods based on your level of commitment to affordability, accessibility and climate compatibility. In Alberta MLI Select allows qualifying -family projects to access higher loan-to-value ratios, extended amortization periods of up to 50 years and reduced insurance premiums. This changes how investors structure acquisitions in secondary markets where rental demand remains strong. Real-World Impact: What MLI Select Means for Your Deal Let me give you an example of how MLI Select can transform a deal. With up to 95 percent financing you can buy a $5 million building with $250,000 down. With a 50-year amortization your monthly payments are significantly lower than they would be with a 25-year amortization. This improves your cash flow from day one. The interest rates available through MLI Select are also more competitive. When you combine these factors the program can be the difference between a deal that works and one that does not. Common Pitfalls and How to Avoid Them MLI Select is powerful. It has challenges. CMHC changed its premium schedule in July 2025. Added surcharges. The minimum 50-point threshold means you need to plan. You cannot assume you will qualify. You need a strategy. The affordability pathway often provides the single lever in Alberta but it requires a long-term commitment to keeping units below market rent. The energy efficiency pathway is getting tougher with the September 30 deadline approaching. My advice is to work with professionals who understand the program. They can help you structure your deal to maximize points and unlock the possible terms. Conclusions CMHC MLI Select is transforming -family investing in Alberta in 2026. With its points-based system rewarding affordability, energy efficiency and accessibility the program offers financing terms. For investors who meet the requirements and the September 30 2026 10

Scroll to Top

Compare