The Fixed Charge Coverage Ratio (FCCR) is a solvency ratio that measures a company’s ability to pay its financial obligations, such as interest fees, debt payments, and lease expenses, using its operating earnings. FCCR is what provides insight into a company’s financial health and also what helps banks assess loan eligibility. Understand that having a higher FCCR indicates stronger financial health, suggesting the company can manage its fixed charges and take on additional debt responsibly. However, on the other hand, a lower FCCR signals higher financial risk.
Learning about a company’s FCCR helps investors assess debt-servicing ability before investing. This blog further covers how to calculate the fixed charge coverage ratio and its formula. So, keep reading to learn more.
Fixed Charge Coverage Ratio Explained
The fixed charge coverage ratio measures the costs a company is obliged to pay regardless of whether sales are high or low. Fixed charges largely remain unchanged, unlike variable costs that rise and fall with production. This is why fixed charges have to be paid on time. Having a higher FCCR is favourable because it means the company generates enough earnings to meet all financial obligations comfortably, making it resilient during difficult business conditions.
However, a lower FCCR tells the opposite, indicating the company could struggle to meet its fixed commitments in case profits decline. This is why FCCR is very useful for assessing a company’s debt-servicing ability, financial stability, and overall solvency before making any investment decisions.
How Do You Calculate the Fixed Charge Coverage Ratio?
To calculate FCCR, it is necessary to add earnings before interest and taxes to fixed charges before tax. Then divide by the total of fixed charges before tax and interest. The fixed charge coverage ratio formula is as follows: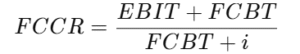
Where:
EBIT = Earnings Before Interest and Taxes
FCBT = Fixed Charges Before Tax
i = Interest
Know that the purpose of calculating FCCR is to determine how well earnings cover fixed charges. It is a critical tool for evaluating a company’s financial stability, which allows lenders to favour companies with a higher FCCR, as it suggests stronger financial health.
How Landlords Use Fixed Charge Coverage to Stop Rental Defaults Before They Happen
Landlords, especially in commercial real estate, use the fixed charge coverage ratio as a financial diagnostic tool to measure a tenant’s corporate health and stop rental defaults before they happen. As for why landlords target FCCR, it broadens the scope. FCCR treats rent as a non-negotiable, fixed financial burden equivalent to senior debt. While corporate FCCR measures operating income against debt and lease obligations, a landlord’s version compares a tenant’s verifiable net monthly income or cash flow with their total fixed monthly commitments. This includes insurance, car payments, proposed rent, and minimum debt or credit card payments.
Landlords often look for an FCCR ratio above 1.25 to 1.50. Note that a ratio below 1.0 means the tenant’s income does not cover their basic fixed costs, indicating a high risk of rental default. Landlords find it useful to identify cash flow squeezes before a missed rent check happens by re-evaluating this ratio during lease renewals or when financial red flags appear.
Why Hiring a Professional Property Management Company Helps
Hiring a professional property management company can be helpful in stopping rental defaults before they happen, as it uses standardized, institutional-grade financial analysis and income-to-debt verification tools rather than relying on gut feelings or basic paystub checks. Professional property management companies enforce strict collection timelines and utilize automated payment portals to track warning signs early.
In addition, they are well-versed in local tenant laws, lease guarantees, and structured payment plans, all of which minimize vacancies and costly eviction proceedings. Partnering with a professional team safeguards consistent cash flow and protects long-term asset profitability, especially in a place like Calgary.
If you’re looking for a well-experienced property management company in Calgary, Alberta, Green Casa Commercial is a great choice. It provides services including property management, construction consultancy, and capital investments. Green Casa is a reputed property management company that offers expert solutions for residential, commercial, condo, and multifamily properties.
The team consists of professionals who have expertise in engineering, finance, and deep local market knowledge, ensuring the protection of property owners while allowing their growth in real estate investments. They help with tenant placement, rent collection, lease management, maintenance coordination, and financial reporting, thereby covering every aspect of effective property management.
Conclusion
Performing deep financial underwriting and managing risk requires specialized expertise, and partnering with a professional property management firm in Calgary can protect your investments. Green Casa is well known for their reliable service, positive client experiences, and commitment to sustainable, long-term value. They have 5+ years of experience, and their sole focus is to protect clients’ investments, deliver consistent returns, and eliminate the day-to-day hassle of ownership. Choosing them can reduce your workload and enhance property performance, making it easier for your investments to thrive in Calgary’s competitive real estate market.
Frequently Asked Questions (FAQs)
A company with a higher FCCR indicates stronger financial health and a potential to manage additional debt responsibly.
Lenders use FCCR to analyze the amount of cash flow a company has available for debt repayment.
Yes, FCCR can be negative if a company has an operating loss.
Hafil Perincheeri
Co-Founder & Director
Hafil Perincheeri is an engineer-turned-realtor, investor, and builder based in Calgary, Canada. As Co-Founder and Director of Greencasa, he specializes in home flips, property development, and investment strategies. Since 2019, he has guided clients in home buying, multifamily investing, and financing options like CMHC and MLI Select, ensuring transparent, informed decisions.